---
title: "1099-K and 1099-NEC: Reconcile Payments Without Double Counting"
description: "Received both 1099-K and 1099-NEC? Match payment records, identify confirmed overlap, explain fees and refunds, and request the right issuer correction."
url: "https://blog.checkstubsonline.com/1099-k-vs-1099-nec-overlap"
datePublished: "2026-11-14"
---
# 1099-K and 1099-NEC: Reconcile Payments Without Double Counting
Received both 1099-K and 1099-NEC? Match payment records, identify confirmed overlap, explain fees and refunds, and request the right issuer correction.
Published: 2026-11-14
By [Check Stubs Online Editorial Team](https://blog.checkstubsonline.com/editorial-policy#editorial-team)
**If Form 1099-K and Form 1099-NEC may include the same payment, reconcile the transaction records before adding the forms together.** Card and qualifying third-party network payments have reporting rules that differ from direct nonemployee payments. Confirm any overlap by date, client and payment reference, request issuer corrections where needed, and report the supported income without counting a receipt twice.
Reviewed November 14, 2026 · U.S. business-service payment reconciliation. The fictional example uses one business, one calendar year, actual received payments and separately documented refunds and fees. It excludes personal-property sales, gifts, shared terminals, entity changes and special reporting categories. It is not a tax-return entry template.
Two forms do not necessarily mean two sets of earnings. They also do not prove that one form is wrong. A client may pay through both a card processor and a direct check, while each issuer summarizes a different view of those transactions. The source ledger has to resolve the relationship.
## In this guide
1. [Understand the reporting roles](#overlap-forms)
2. [Build a payment-level worksheet](#overlap-file)
3. [Reconcile an original overlap example](#overlap-example)
4. [Explain fees and smaller deposits](#overlap-bank)
5. [Request the right correction](#overlap-correct)
6. [Keep payer tools in their role](#overlap-tool)
7. [1099 overlap questions](#overlap-faq)
## Why the form type and payment channel matter
The [IRS introduction to Form 1099-K](https://www.irs.gov/businesses/understanding-your-form-1099-k) explains that payment card companies and certain settlement organizations report payment activity. Form 1099-NEC instead reports covered nonemployee compensation under its own rules. The names describe reporting categories, not two automatically separate income streams.
The [IRS instructions for Forms 1099-MISC and 1099-NEC](https://www.irs.gov/instructions/i1099mec) state that payment-card transactions and qualifying third-party network transactions reportable under section 6050W are not also reportable on those forms. This is why a payer’s inclusion of a card payment on a 1099-NEC can require investigation.
Do not assume every bank transfer or app payment falls in the same category. Establish the actual payment method and settlement arrangement. A direct payment can be different from a transaction processed through a reporting network, even when both eventually appear as electronic bank credits.
Reporting thresholds and taxability are separate questions. The [IRS recipient guidance](https://www.irs.gov/businesses/what-to-do-with-form-1099-k) instructs readers to use the forms with other records and include income that was not reported on a form. A missing form does not make genuine business income disappear; see [reporting self-employment income without a 1099](https://blog.checkstubsonline.com/report-self-employment-income-without-1099).
## Build a worksheet with one row per received payment
Collect the client’s remittance details, processor transaction export, bank settlements, invoices, receipts and annual forms. Confirm the same business name, taxpayer identity and calendar year. A processor’s merchant name might differ from a client’s business name, so labels alone may not reveal a match.
For each payment, record the amount before fees, client, date, invoice reference, transaction identifier, channel and where it appears in the annual summaries. Keep the processor fee, refund and settlement identifiers in separate columns. One bank deposit may combine many payments and should not automatically become one sale in the ledger.
**Payment-level evidence for a potential overlap**
| Evidence | What it can establish | What it cannot establish alone |
| --- | --- | --- |
| Client remittance or payment reference | Which invoice and payment the client identifies | Whether every processor transaction is included |
| Processor export | Gross transactions, fees and settlement connections | That a separate direct check is already in its total |
| Bank entry | Money credited, debited or still pending | The gross receipts before processor adjustments |
| Annual information form | What an issuer reported for the stated year | The complete business profit or the exact source of every deposit |
The [IRS business-record guidance](https://www.irs.gov/businesses/small-businesses-self-employed/what-kind-of-records-should-i-keep) emphasizes books supported by documents showing income and expenses. Preserve those documents rather than keeping only the final spreadsheet. If a reference cannot be matched, label it unresolved and ask for the missing detail.
## Original example: $12,000 on forms, $10,000 in unique receipts
Assume a fictional service business received $7,000 through a payment-card processor during one calendar year. Client A supplied $2,000 of those card receipts; other clients supplied $5,000. The processor’s Form 1099-K reports $7,000 gross.
Client A also paid the business $3,000 directly by check. Suppose Client A’s Form 1099-NEC reports $5,000 because it includes both the direct checks and the same $2,000 card payment. Assume the transaction records confirm this exact overlap and no other differences.
Adding the forms produces $12,000: $7,000 plus $5,000. Removing the confirmed repeated $2,000 leaves $10,000 of unique gross receipts before refunds and fees. The independent ledger reaches the same amount: $7,000 card receipts plus $3,000 direct checks.
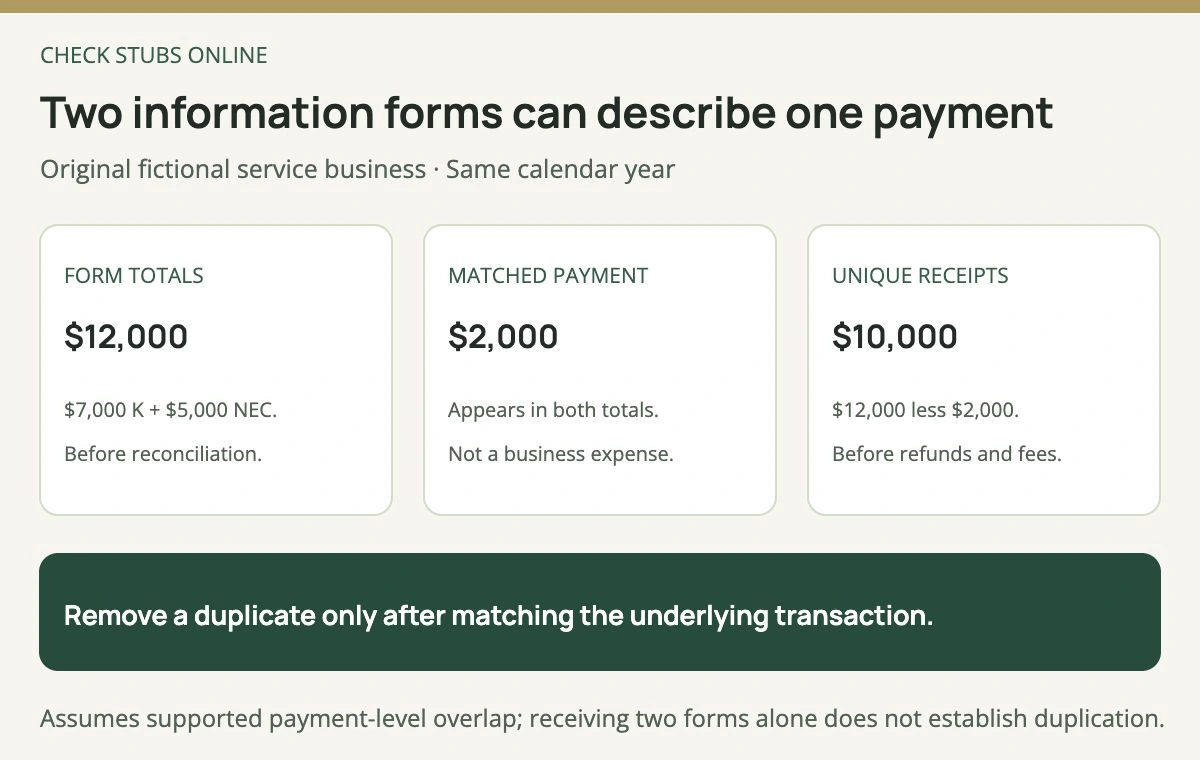
The $2,000 reconciliation removes a second count of one receipt. It is not an additional business expense or permission to ignore an entire form.
If the $5,000 NEC amount instead described different payments, the $2,000 subtraction would be wrong. If only part of a client payment overlaps, match that part. Similar totals, identical client names or the mere presence of two forms are insufficient evidence.
Under the assumed facts, ask Client A to review the payment-card reporting rule and its NEC amount. Keep the original while the issuer investigates. A corrected form should follow the actual supported payment categories, not simply the number you prefer to see.
## Reconcile refunds and fees separately from duplicate reporting
Continue the same fictional example with $400 of supported customer refunds and $210 of processor fees, all within the same year. Assume those are the only processor settlement adjustments, and no funds are pending or held. The $7,000 card gross then bridges to $6,390 of card settlement cash.
Add the separate $3,000 direct checks, with no other adjustments assumed, to reach $9,390 after these refunds and fees. The same bridge starts from $10,000 unique receipts and subtracts $400 and $210. It does not subtract the confirmed $2,000 overlap a second time.
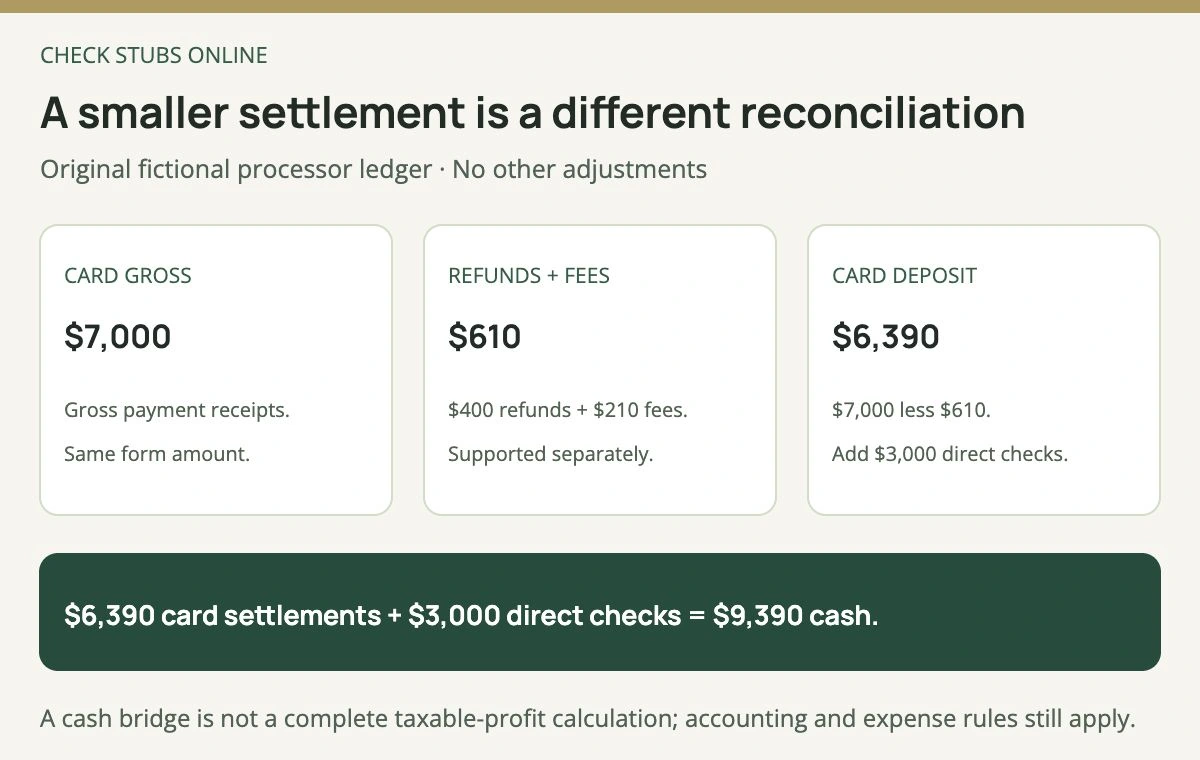
The settlement bridge explains the cash received under the example’s assumptions. It does not determine every deductible expense or calculate income or self-employment tax.
IRS recipient guidance notes that the 1099-K gross amount is not reduced for items such as fees and refunds. A gross-to-deposit difference therefore does not establish a form error. Document the actual adjustments, their timing and proper tax treatment rather than using the bank credit as a substitute for gross receipts.
For a real business, reserves, chargebacks, sales taxes, shipping, different accounting methods and year-end settlement timing can complicate the bridge. Personal transactions or a shared terminal also require separate treatment. Keep these cases outside this simple service-business worksheet until their facts are reviewed.
## Request a correction from the issuer responsible for the error
If the NEC includes an incorrectly reported card payment, contact that payer with the payment references and relevant reporting rule. If the K contains incorrect information, follow the [IRS process for contacting its issuer or payment settlement entity](https://www.irs.gov/businesses/what-to-do-with-form-1099-k). The issuer of one form cannot necessarily correct the other issuer’s record.
Use a secure channel and provide only the information needed to locate the payment. Preserve the request, response, original form and any correction with the reconciliation. A personal spreadsheet can explain what happened but does not amend the payer’s government-filed return.
Do not let an unresolved correction request become an assumption that filing deadlines stop. Review the current IRS instructions for the actual return and form year, and obtain qualified help where the reporting remains uncertain. The treatment for an erroneous K, an overlapping NEC and a personal-property sale is not one universal negative-income entry.
Our [1099 retrieval guide](https://blog.checkstubsonline.com/get-copy-of-1099-online) helps locate issuer records. The [NEC versus MISC guide](https://blog.checkstubsonline.com/1099-nec-vs-1099-misc) addresses a different distinction: which nonemployee payment category a payer is reporting.
## A payer’s PDF builder does not correct a recipient’s mismatch
The [Check Stubs Online 1099-NEC builder](https://www.checkstubsonline.com/forms/1099-nec/create) is for supported document preparation by an authorized payer. Confirm its currently available form year and scope before entering reconciled payment records. Its existence does not mean a recipient should create a new payer-issued form to replace an unresolved statement.
Preparing a PDF also does not transmit a correction to the IRS. The actual payer must follow the applicable filing and furnishing process. If you are organizing your own business income, keep the reconciliation and source records in your own name; do not present them as an independent issuer’s certification.
## 1099 overlap questions
### Should I always add K and NEC amounts?
Reconcile them first. Add distinct receipts, but do not count the same confirmed payment twice.
### Does a smaller bank deposit prove the K is wrong?
No. The form reports gross payment activity, while fees, refunds and other settlement adjustments may reduce the deposit.
### Can I discard the NEC if I also have a K?
No. It may include separate direct payments. Keep both and establish their transaction-level relationship.
### Is the matched overlap a business deduction?
No. Removing a duplicate count and deducting an eligible business expense are different operations.
The Check Stubs Online Editorial Team reviewed current IRS payment-reporting and business-record guidance and independently checked the overlap and settlement examples.
## Relevant document tool
Reconcile reportable payments before preparing a 1099-NEC
Check the actual payment channel, supported amounts and builder’s available year before preparing a payer document.
[Review the 1099-NEC builder](https://www.checkstubsonline.com/forms/1099-nec/create)
Recipients should request issuer corrections. Preparing a PDF does not amend a filed information return or determine taxability.
## Related guides
- [How to Report Self-Employment Income Without a 1099](https://blog.checkstubsonline.com/report-self-employment-income-without-1099)
- [1099-NEC vs. 1099-MISC: Differences and 2026 Rules](https://blog.checkstubsonline.com/1099-nec-vs-1099-misc)
- [How to Get a Copy of Your 1099 Online: Payer and IRS Options](https://blog.checkstubsonline.com/get-copy-of-1099-online)