---
title: "Expense Reimbursements on a Pay Stub: Wages, Advances and Records"
description: "Separate wages from expense reimbursements on your pay stub. Review accountable arrangements, allowances, advance returns and a worked payment reconciliation."
url: "https://blog.checkstubsonline.com/expense-reimbursements-pay-stub"
datePublished: "2026-11-18"
---
# Expense Reimbursements on a Pay Stub: Wages, Advances and Records
Separate wages from expense reimbursements on your pay stub. Review accountable arrangements, allowances, advance returns and a worked payment reconciliation.
Published: 2026-11-18
By [Check Stubs Online Editorial Team](https://blog.checkstubsonline.com/editorial-policy#editorial-team)
**An expense reimbursement on a pay stub is not automatically taxable wages or extra take-home earnings.** Under a qualifying accountable arrangement, supported employee business costs can be repaid separately from wages. Payments under a nonaccountable arrangement generally receive wage treatment. Check the plan, substantiation and any excess advance rather than relying on the word “reimbursement.”
Reviewed November 18, 2026 · U.S. federal employee business-expense reimbursement records. The examples assume ordinary qualifying business expenses and the stated plan conditions. They do not establish deductible travel, a mileage rate, a tax calculation, overtime treatment or state reimbursement rights.
A deposit can combine wage pay with repayment of money an employee spent for work. Reading that entire deposit as earnings can overstate the pay available for a household budget or income review. Start with the separate lines and the expense report behind them.
## In this guide
1. [Identify the arrangement](#reimb-types)
2. [Reconcile a combined deposit](#reimb-deposit)
3. [Connect the expense evidence](#reimb-evidence)
4. [Settle an advance and its excess](#reimb-advance)
5. [Review allowances and statement labels](#reimb-labels)
6. [Resolve a reporting mismatch](#reimb-correct)
7. [Prepare an accurate record](#reimb-tool)
8. [Expense reimbursement questions](#reimb-faq)
## The arrangement matters more than the payroll label
[IRS Publication 15](https://www.irs.gov/publications/p15) distinguishes accountable and nonaccountable reimbursement arrangements. Accountable treatment requires qualifying employee business costs, adequate substantiation within a reasonable time and a timely return of amounts beyond supported expenses. Renaming salary as an expense payment does not satisfy those requirements.
The same guidance excludes qualifying accountable payments from wages and treats nonaccountable payments as wages subject to the applicable payroll taxes. When wages and reimbursement are combined, the employer must identify the reimbursement amount. A separate line helps explain the payment, but the line itself does not establish eligibility.
**Review the reason for the expense payment**
| Situation | What to check | Record to keep |
| --- | --- | --- |
| Repayment of an approved business cost | Business connection, substantiation and plan conditions | Expense report, support and approval |
| Advance before spending occurs | How and when the employee must account for it | Advance record and settlement |
| Flat allowance | Which rules and substantiation method apply | Policy and evidence supporting the allowance |
| Unused advance amount | Whether excess was returned within the applicable period | Return confirmation and employer reconciliation |
| Payment labeled reimbursement but replacing salary | Whether the arrangement actually meets accountable requirements | Original pay terms and payroll explanation |
Do not use this table to classify a contractor’s invoice, a health benefit or a relocation arrangement without reviewing its own rules. The subject here is employee business-expense repayment. Our [employer-paid benefits guide](https://blog.checkstubsonline.com/employer-paid-benefits-pay-stub) covers another reason informational lines can differ from wages.
## Original example: wages plus a $240 reimbursement
Assume a fictional employee has $1,800 of gross wages for a pay period. Total wage deductions are assumed to be $360, producing $1,440 of wage take-home pay. The employer also repays $240 of properly supported qualifying business costs under an accountable arrangement.
If both amounts arrive in one payment, the deposit is $1,440 + $240 = $1,680. It is not $1,680 of wage take-home pay. The $240 replaces money the employee previously spent for the employer’s business under the stated facts.
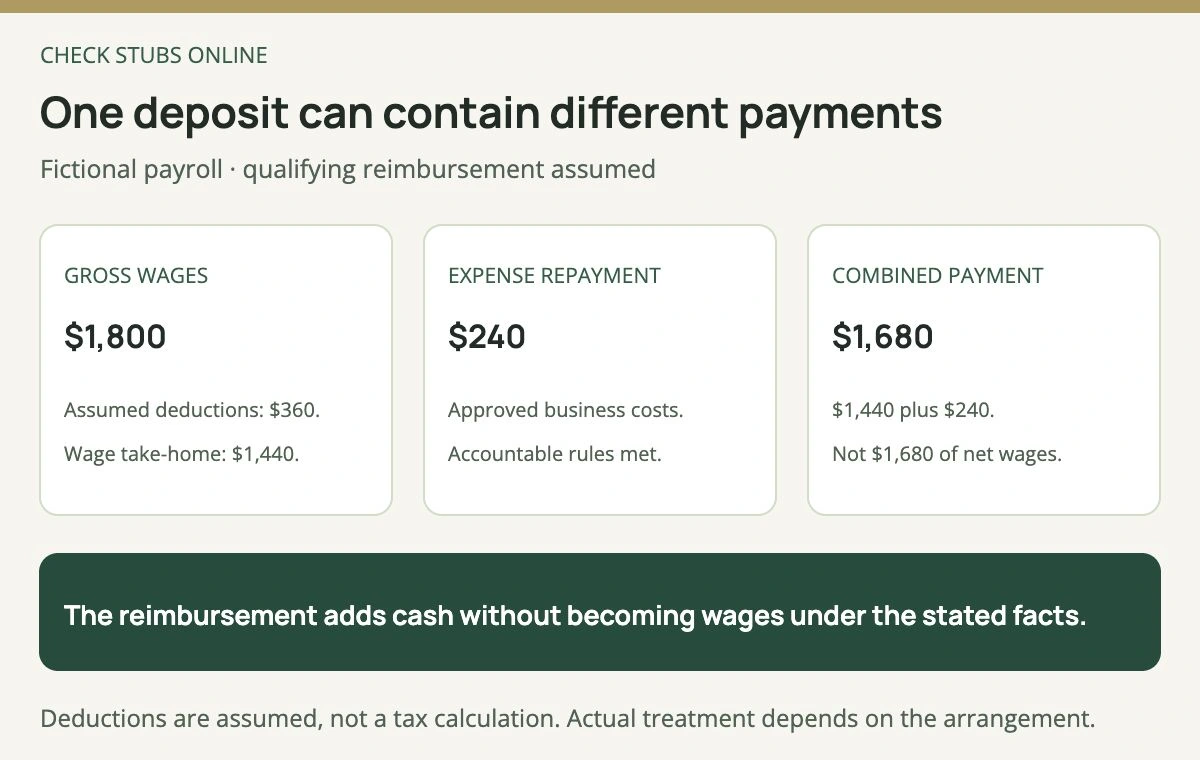
The $360 deductions are an assumption used to demonstrate the payment bridge. No withholding rate or individual tax result is implied.
For budgeting, keep the expense outflow beside the repayment so the reimbursement is not mistaken for a recurring raise. For a document review, show the wage statement and the expense explanation rather than asking a bank deposit to prove every part of compensation.
The arithmetic also catches a common double count: do not add the $240 again after using the full $1,680 bank deposit. Conversely, do not subtract the same expense reimbursement twice when moving from the statement to the bank. The [gross-to-net reconciliation guide](https://blog.checkstubsonline.com/gross-vs-net-pay) explains the ordinary wage bridge before this additional component.
## Connect the expense report with the payment
[IRS Publication 463](https://www.irs.gov/publications/p463) describes records supporting travel and other covered expenses, including evidence of the amount and business purpose. A bank charge alone may not explain the business activity or separate a personal component. Follow the relevant substantiation rules and the employer’s actual reporting process.
Build a trail from the transaction to the expense report, approval and repayment. Useful identifiers include the report number, expense date, business purpose, approved amount and payroll or accounts-payable reference. If several reports are combined, list each approved amount once and check the total.
Record approval and payment status separately. A submitted expense claim is not proof that it has been approved or paid. If the employer approved $240 but the bank shows $200, ask whether another amount is pending, disallowed or paid through a different channel before changing the payroll record.
Preserve the original receipts and any explanation of a missing receipt. Do not manufacture support to make a claim fit. A clear exception note and the employer’s documented response are more useful than an edited or unexplained transaction image.
## Original advance example: $500 received, $410 supported
Now assume the employee receives a $500 advance for qualifying business costs. The final supported amount is $410. Under the example’s accountable-plan conditions, the employee returns the $90 difference within the applicable reasonable period and keeps the employer’s confirmation.
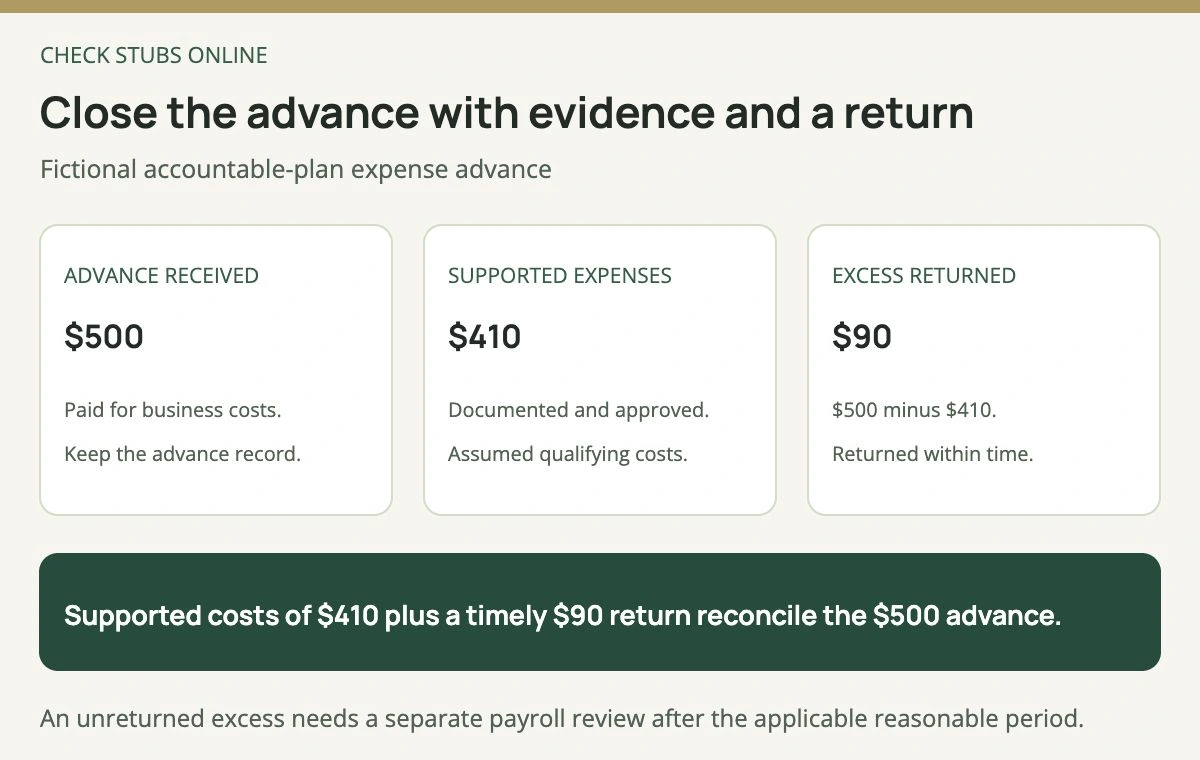
The advance settlement is $410 of supported costs plus a $90 return. Do not record the later settlement as another $500 payment.
The check is $500 − $410 = $90, and $410 + $90 = $500. Match the return to the original advance rather than merely showing a negative entry with no explanation. The date and recipient of the return should be identifiable in the retained evidence.
Publication 463 explains that excess not timely returned can receive nonaccountable treatment. A plan’s general accountable label does not automatically shelter an unsupported balance. If the fictional $90 were not returned, payroll would need to review that excess and the applicable timing instead of assuming the entire advance had been settled.
Do not independently deduct the balance from the employee’s next paycheck without reviewing the permitted process. Tax classification, repayment authorization and any state wage-deduction requirements are separate questions. This guide does not decide those state requirements.
## A flat allowance still needs its own support
A repeated payment called “travel,” “car allowance” or “per diem” is not automatically excluded from wages. Some approved allowance methods use special substantiation rules. The applicable method, actual business activity and excess amounts must still be reviewed; a label is not a substitute for that work.
Do not infer a mileage rate from the amount on a statement or copy a federal rate for a different year or purpose. Ask which policy and method the employer used. An employment offer’s allowance description should be checked against the actual expense arrangement and payroll treatment.
Statement presentation also varies. A system may display reimbursements outside the earnings table, in an additional-payment section or through a separate payment service. Look for the payment bridge and expense reference rather than assuming every payroll layout uses the same column.
A year-to-date reimbursement total is not automatically part of YTD gross wages. Our [YTD gross-pay guide](https://blog.checkstubsonline.com/ytd-gross-pay) explains why the field definition matters. Keep a separate expense ledger if you need to reconcile annual repayment totals.
## Ask payroll to explain a mismatch before changing a form
Identify whether the issue is an unpaid claim, a wrong payment amount or disputed wage treatment. Send the expense-report reference, the affected payroll date and the exact difference through the employer’s established process. Keep sensitive transaction information in the appropriate secure channel.
If a reimbursement appears in wages despite meeting the accountable-plan conditions, Publication 463 directs employees to seek an employer correction. Confirm the facts and the relevant statement year. A corrected expense report does not itself correct a filed wage statement.
Our [pay-stub error guide](https://blog.checkstubsonline.com/pay-stub-errors-correction) explains how to track an issuer correction. The [W-2 correction guide](https://blog.checkstubsonline.com/reissued-w2-vs-w2c) covers the distinct annual-record process. Keep the original and corrected records together so a later reviewer can follow the change.
## Prepare records without converting expenses into wages
The [Check Stubs Online pay-stub maker](https://www.checkstubsonline.com/pay-stub-maker) supports document preparation from accurate authorized payroll information. It does not decide whether an expense qualifies, approve a reimbursement claim or implement the employer’s accountable plan.
Review whether the selected format can clearly represent the supported payment components. Do not force an expense repayment into salary simply to match a bank deposit. Keep the expense settlement or separate employer record if that is needed to explain the payment accurately.
## Expense reimbursement questions
### Does a reimbursement always increase taxable wages?
No. Treatment depends on the arrangement and whether its conditions are met.
### Is a larger bank deposit evidence of a raise?
Not by itself. Separate wage pay, expense repayment and other supported components.
### Does an advance disappear from the records when receipts are submitted?
No. Reconcile the advance to supported costs and any return or other required settlement.
### Can I fix the employer’s wage reporting by editing my copy?
No. Ask the issuer to review the underlying treatment and make an appropriate correction.
The Check Stubs Online Editorial Team reviewed current IRS reimbursement guidance and independently checked both original payment reconciliations.
## Relevant document tool
Keep wages and expense repayments clear
Prepare an accurate payroll statement and retain the separate expense evidence that supports any reimbursement.
[Review the pay-stub maker](https://www.checkstubsonline.com/pay-stub-maker)
A document maker does not establish accountable-plan eligibility, approve expenses or determine tax or state reimbursement treatment.
## Related guides
- [Pay Stub Errors: How to Request and Track a Correction](https://blog.checkstubsonline.com/pay-stub-errors-correction)
- [YTD Gross Pay: Meaning, Calculation and Correction Checks](https://blog.checkstubsonline.com/ytd-gross-pay)
- [Employer-Paid Benefits on a Pay Stub: What Changes Your Pay?](https://blog.checkstubsonline.com/employer-paid-benefits-pay-stub)