---
title: "Missing W-2? Form 4852, Payroll Records and Filing Steps"
description: "Missing or incorrect W-2? Review the IRS Form 4852 process, current tips and overtime limits, a checked payroll example and what to do when the W-2 arrives."
url: "https://blog.checkstubsonline.com/missing-w2-form-4852"
datePublished: "2026-11-11"
---
# Missing W-2? Form 4852, Payroll Records and Filing Steps
Missing or incorrect W-2? Review the IRS Form 4852 process, current tips and overtime limits, a checked payroll example and what to do when the W-2 arrives.
Published: 2026-11-11
By [Check Stubs Online Editorial Team](https://blog.checkstubsonline.com/editorial-policy#editorial-team)
**When your employer has not supplied a usable W-2, begin with its payroll contact and then use the applicable IRS procedure; Form 4852 may support filing when a usable W-2 is still unavailable.** Build its estimates from the correct year’s records, explain the method and keep evidence of your retrieval attempts. Current IRS guidance separately limits using Form 4852 amounts to establish qualified tips or overtime deductions.
Reviewed November 11, 2026 · U.S. federal missing or incorrect employee W-2 records. The original example concerns ordinary 2025 wages, with no qualified tips or overtime deduction. Retirement distributions, state filing procedures and individualized deduction eligibility require their own review.
A missing form creates two jobs: keep seeking the issuer’s information and prepare a defensible filing record. Recreating an official-looking W-2 yourself does not accomplish either job. The useful question is what records support each amount, which facts remain unresolved and which official procedure fits the situation.
## In this guide
1. [Choose the correct missing-form route](#missing-route)
2. [Observe the tips and overtime limit](#missing-scope)
3. [Build a year-specific evidence file](#missing-records)
4. [Reconstruct the original example](#missing-example)
5. [Separate the wage and tax fields](#missing-fields)
6. [Review filing and later corrections](#missing-filing)
7. [Missing-W-2 questions](#missing-faq)
## Start with the employer, then the IRS process
The [IRS missing or incorrect W-2 guidance](https://www.irs.gov/filing/if-you-dont-get-a-w-2-or-your-w-2-is-wrong) starts with contacting the employer. Check the delivery address and the employer’s approved payroll portal. A lost login and an issuer that never supplied a statement are different problems; our [former-employer W-2 guide](https://blog.checkstubsonline.com/w2-from-former-employer) covers retrieval.
For an unresolved form by the end of February, the IRS describes contacting it at 800-829-1040. Have identifying and employer information available through that official channel. Keep private tax identifiers out of ordinary email, public comments and shared example documents.
[Form 4852](https://www.irs.gov/forms-pubs/about-form-4852) is the IRS substitute associated with missing or incorrect W-2, W-2c or 1099-R information. It is not a universal substitute for every 1099, every income record or every document a lender requests.
Use the [official Form 4852 and its instructions](https://www.irs.gov/pub/irs-pdf/f4852.pdf) for the form itself. A completed substitute belongs in the tax-filing process it supports; it does not become an employer-issued W-2 or an independent certification of employment.
## Keep the current tips and overtime qualification beside the advice
The [current IRS W-2 FAQ](https://www.irs.gov/faqs/irs-procedures/w-2-additional-incorrect-lost-non-receipt-omitted) expressly identifies exceptions involving qualified tips and qualified overtime compensation. Amounts on Form 4852 cannot establish those deductions under the rules described there. A general missing-W-2 procedure is therefore not enough to decide how either deduction should be documented.
If that issue applies, follow the FAQ’s linked current deduction guidance for the actual year and facts. Do not relabel ordinary wages as qualifying tips or overtime, and do not treat an estimate of total annual pay as evidence of a separate deduction. Our example deliberately excludes both deductions so that its wage reconciliation does not imply otherwise.
Likewise, the absence of a wage form does not turn employee wages into self-employment income. Actual worker status and income type matter. For genuinely independent work, see [reporting business income without a 1099](https://blog.checkstubsonline.com/report-self-employment-income-without-1099); unemployment reporting has its own [1099-G record process](https://blog.checkstubsonline.com/1099-g-online-government-payment-guide).
## Build one evidence folder for the employer and tax year
Start with the most complete payroll statement for the relevant calendar year, then locate any later correction, off-cycle payment or separate statement. Label which totals are cumulative and which describe only one payment. A December statement may be the last regular statement without being the final record of every payment.
Record the employer, employee, payment dates and calendar year. Keep the original files intact and make a separate reconciliation worksheet. If several employers used the same payroll platform, a shared login is not a reason to combine their wage information into one issuer record.
A bank deposit can corroborate receipt of cash but generally shows a net transfer. It does not break that transfer into taxable wage bases, income-tax withholding, benefit deductions and other payroll items. Keep deposits as supporting evidence rather than assigning their amount directly to a W-2 wage field.
**A working missing-W-2 evidence index**
| Record | What to establish | Limitation |
| --- | --- | --- |
| Last complete year-to-date payroll statement | Cumulative amounts through its stated cutoff | May omit a later off-cycle payment or correction |
| Separate payroll or adjustment record | Whether a payment is outside that cumulative total | Do not add it again if already included |
| Employer correspondence | Dates, issue raised and response received | A request is not proof of the wage amount |
| Bank transaction history | Payment receipt and date | Net deposits do not identify every tax field |
| Available IRS wage transcript | Information returns the IRS has received | Availability and contents are not identical to a complete W-2 |
The [IRS transcript overview](https://www.irs.gov/individuals/transcript-types-for-individuals-and-ways-to-order-them) describes wage-and-income information drawn from received information returns. Check availability for the needed year rather than assuming a transcript already contains a missing or corrected employer submission. An empty search result is not evidence that no wages were earned.
Maintain a short unresolved-items list. For example: “Confirm whether the December adjustment is already included” is more useful than silently adding it. Each uncertainty should have an owner, an attempted source and a status. Preserve what the employer actually said rather than converting an unanswered question into a confirmed fact.
## Original example: add a separate payment only once
Assume a fictional employee’s last regular 2025 payroll record shows $46,800 cumulative ordinary wages and $4,235 federal income tax withheld. A separate December off-cycle record shows $1,250 wages and $137 federal withholding. The employer’s records in this example establish that the off-cycle amounts were not included in the regular year-to-date totals.
The supported wage total is $48,050, and the supported federal withholding total is $4,372. The employee does not add every historical year-to-date figure together. Nor does the employee multiply the last paycheck by a presumed number of checks to invent an annual result.
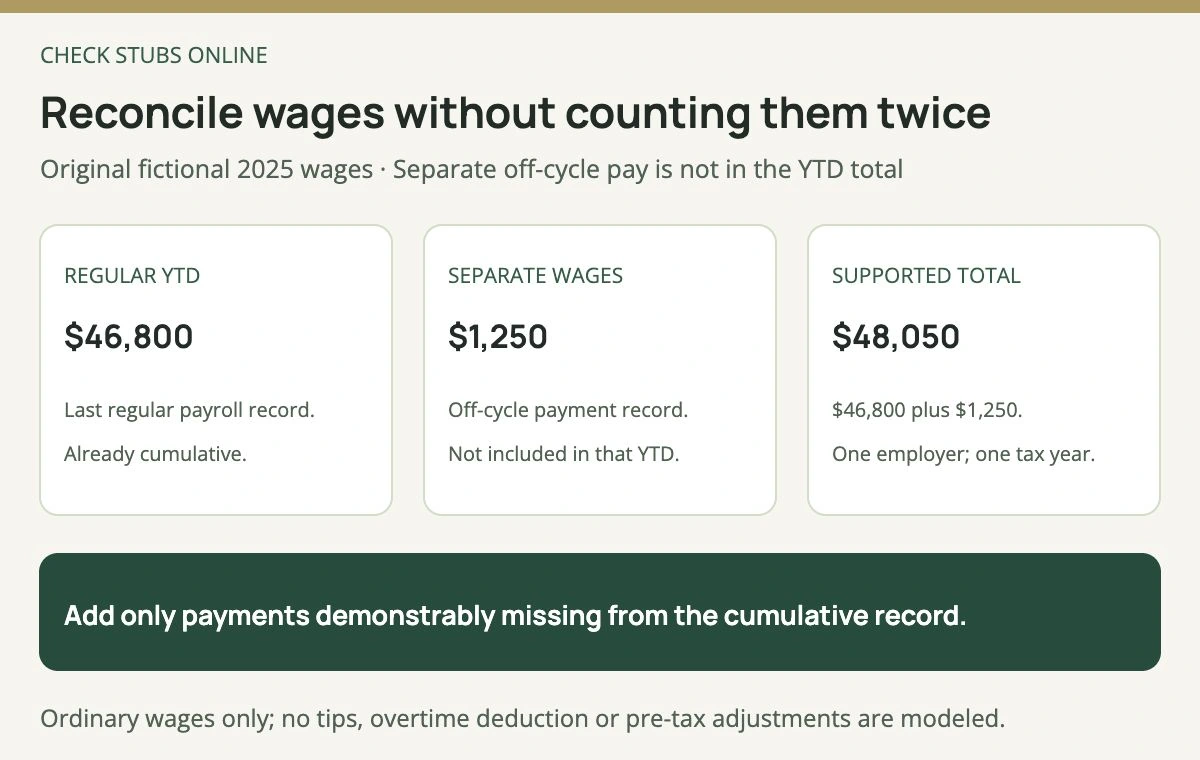
The separate $1,250 is added because the stated example records establish that the $46,800 cumulative amount excludes it.
This example uses one employer, no pre-tax or noncash adjustments, no tips and no qualified overtime deduction. Its three wage bases are assumed equal. Those assumptions make the example transparent; they do not establish that every real worker’s W-2 wage boxes should match.
If the separate payment were already included, adding it would overstate wages by $1,250 and federal withholding by $137. That alternative is a duplicate-counting test, not a second valid answer. Confirming coverage is as important as adding the numbers correctly.
## Keep withholding amounts tied to their actual records
The fictional regular statement also records $2,901.60 employee Social Security tax and $678.60 employee Medicare tax. The separate payment records $77.50 and $18.13 respectively. Adding the actual record entries yields $2,979.10 and $696.73.
The [2025 employer tax guide](https://www.irs.gov/pub/irs-prior/p15--2025.pdf) supplies the ordinary 6.2% Social Security and 1.45% Medicare rates used as an independent reasonableness check here. Withholding entries remain the supplied example records, not unknown amounts invented by multiplying wages. The Medicare off-cycle result is rounded to cents; payroll-level rounding can matter.
**Original fictional 2025 payroll reconciliation; amounts are supplied record entries**
| Record | Wages | Federal withheld | Employee Social Security | Employee Medicare |
| --- | --- | --- | --- | --- |
| Regular cumulative statement | $46,800.00 | $4,235.00 | $2,901.60 | $678.60 |
| Separate off-cycle statement | $1,250.00 | $137.00 | $77.50 | $18.13 |
| Supported combined amounts | $48,050.00 | $4,372.00 | $2,979.10 | $696.73 |
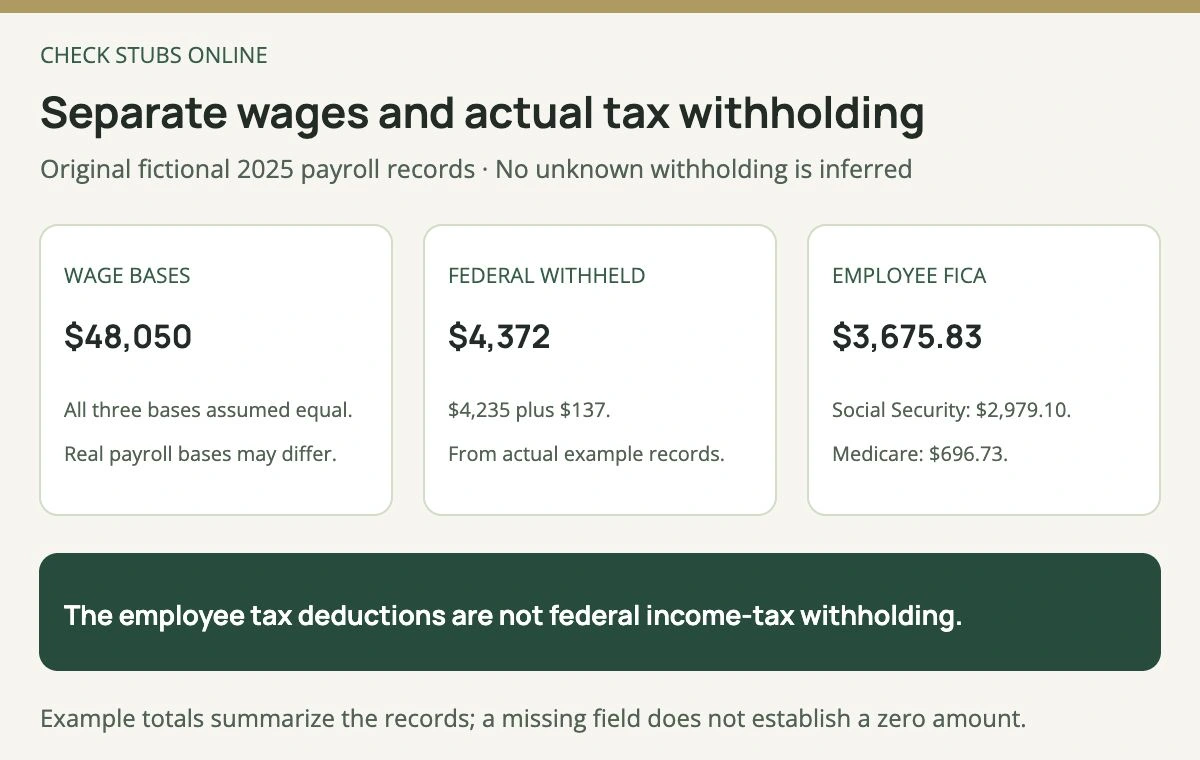
Employee Social Security and Medicare total $3,675.83, separately from the $4,372 federal income-tax withholding.
The Form 4852 instructions distinguish wage bases and withholding categories, exclude the employer’s Social Security and Medicare share, and request the method used to determine amounts and attempts made to obtain the form. Fill those explanations with the actual facts, not sample contact dates copied from another person’s letter.
State or local information is not modeled here. An unverified field is not automatically zero. If a payroll label is unclear, request its definition and compare it with the applicable form instructions. Our [year-end pay-stub and W-2 comparison](https://blog.checkstubsonline.com/year-end-pay-stub-vs-w2) explains why payroll gross and tax wages can differ.
## Review the return, filing timing and later-arriving form
[IRS Topic 154](https://www.irs.gov/taxtopics/tc154) addresses filing when the needed form remains unavailable and amending when a later form reveals that the filed information was wrong. Compare a late W-2 field by field; merely receiving another document does not establish that the return needs the same numerical change in every field.
Keep the filed copy, the substitute, the worksheet and the source evidence together. The Form 4852 instructions call for retaining its copy until Social Security benefits begin to help protect the earnings record. That special instruction should not be replaced with a generic annual cleanup habit.
A missing W-2 does not itself grant more time. The [IRS extension guidance](https://www.irs.gov/filing/get-an-extension-to-file-your-tax-return) distinguishes a timely filing extension from the obligation to pay. Use the actual return year’s deadlines and any applicable relief; do not assume an expired extension window remains open. See our [Form 4868 guide](https://blog.checkstubsonline.com/form-4868-online-tax-extension-guide) for that separate document.
For a supported 2025 return, the [Check Stubs Online Form 1040 preparation tool](https://www.checkstubsonline.com/forms/1040/create) currently offers the 2025 main form; its 2026 option is marked unavailable pending the final IRS original. It does not create Form 4852, assemble every required attachment, e-file the return or make a tax payment. Use the official substitute separately where appropriate and review the complete filing package.
## Missing-W-2 questions
### Can I just use my last bank deposit?
A net deposit does not establish the separate wage and withholding fields. Reconcile payroll records and document unresolved amounts.
### Can last year’s W-2 supply this year’s amounts?
No. It may help locate an employer contact, but another year’s wages are not evidence of the current year’s actual totals.
### Is Form 4852 a substitute for a contractor’s missing 1099-NEC?
No. Its stated substitute-form scope is different. Review the actual income type and the appropriate reporting records.
### What if the employer eventually sends a different W-2?
Compare it with what was filed. Follow the IRS amendment guidance if the return information needs correction, preserving both versions and the reconciliation.
The Check Stubs Online Editorial Team reviewed the current IRS substitute-form process and deduction qualification, inspected the linked tool and independently checked the original payroll reconciliation.
## Relevant document tool
Review the supported 2025 Form 1040
Enter reviewed information for the available year, then inspect the main-form PDF and the complete required filing package.
[Open the Form 1040 tool](https://www.checkstubsonline.com/forms/1040/create)
This tool does not prepare Form 4852, assemble every attachment, e-file a return or pay tax. The 2026 option is currently unavailable.
## Related guides
- [IRS Wage and Income Transcript vs. W-2: What Is Missing?](https://blog.checkstubsonline.com/irs-wage-income-transcript-vs-w2)
- [Year-End Pay Stub vs. W-2: Reconcile the Differences](https://blog.checkstubsonline.com/year-end-pay-stub-vs-w2)
- [How to Get a W-2 From a Former Employer](https://blog.checkstubsonline.com/w2-from-former-employer)