---
title: "Reissued W-2 vs. W-2c: Duplicate Copies and Corrected Amounts"
description: "Learn when you need a reissued W-2 or an employer correction. Compare W-2c fields, avoid double counting and review a return already filed."
url: "https://blog.checkstubsonline.com/reissued-w2-vs-w2c"
datePublished: "2026-11-17"
---
# Reissued W-2 vs. W-2c: Duplicate Copies and Corrected Amounts
Learn when you need a reissued W-2 or an employer correction. Compare W-2c fields, avoid double counting and review a return already filed.
Published: 2026-11-17
By [Check Stubs Online Editorial Team](https://blog.checkstubsonline.com/editorial-policy#editorial-team)
**A reissued W-2 supplies another copy of a record; a W-2c corrects specified information on a previously filed wage statement.** If the amounts are right but your copy is lost, ask the employer for a duplicate. If a name, taxpayer identifier or reported amount is wrong, ask the employer to investigate and use the correction procedure that fits the filing stage and error.
Reviewed November 17, 2026 · U.S. employee W-2 records, using current IRS guidance and the January 2026 W-2c revision. The original example concerns a transcription error in selected fields of a 2025 statement, not a wage repayment or a promised tax refund. Employer filing steps, state requirements and individual return consequences need their own review.
Receiving a second envelope or PDF does not necessarily mean you have another income item. Identify whether it repeats the original, changes a field or corrects a particular earlier filing. That distinction prevents both double counting and overlooking a real change.
## In this guide
1. [Decide whether the problem is a missing copy or wrong data](#w2-copy)
2. [Ask which filing stage and error apply](#w2-stage)
3. [Compare original and corrected amounts](#w2-example)
4. [Read W-2c together with the original](#w2-pair)
5. [Review a return already filed](#w2-filed)
6. [Make a focused employer request](#w2-request)
7. [Keep PDF preparation separate from correction filing](#w2-builder)
8. [Reissue and correction questions](#w2-faq)
## A missing copy and an incorrect record are different problems
If a correct statement was lost or damaged, request another employer-issued copy for the same year. The [IRS W-2 instructions](https://www.irs.gov/instructions/iw2w3) describe the reissued-statement treatment and do not require the paper reissue label on an electronically provided copy. A duplicate delivery does not create another wage payment.
If you still have the original, compare the issuer, year and amounts with the new copy. Two copies of the same statement may be labelled for different filing destinations. Those copy labels are not instructions to enter the wages twice.
If a number or identity field is actually wrong, ask the employer about a correction instead of requesting only another printout. Our [former-employer W-2 guide](https://blog.checkstubsonline.com/w2-from-former-employer) covers retrieval, while this guide focuses on deciding what the replacement or correction means.
**Choose the question to ask the employer**
| Situation | Useful request | Avoid this assumption |
| --- | --- | --- |
| Correct statement, missing personal copy | Please reissue my W-2 for the identified year | A second copy means a second income item |
| Wrong reported wage or withholding amount | Please reconcile the named box with the annual records | Changing the PDF changes the filed information |
| Wrong name or taxpayer identifier | Please investigate the identity information and required correction | A name-only correction necessarily changes tax |
| Wrong address only | Please confirm delivery and the applicable address procedure | Every address fix requires an SSA-filed W-2c |
| Original plus a W-2c received | Which fields were corrected, and which original form does it amend? | The correction is another complete, additional W-2 |
## Filing stage matters to the employer’s correction route
The [IRS W-2c overview](https://www.irs.gov/forms-pubs/about-form-w-2-c) identifies it as the corrected wage-statement form. The detailed W-2 instructions distinguish an error discovered before the original is sent to the Social Security Administration from an error in a form already filed. A “corrected” employee copy and a W-2c are therefore not interchangeable labels for every stage.
Employees should ask the issuer to identify the appropriate procedure. Do not personally mark an original W-2 and assume that this changes government records. Employers also need the correct channel and any related transmittal or payroll-return treatment; producing a PDF is not that filing step.
Address-only problems are a specific exception worth flagging. The instructions generally do not call for an SSA-filed W-2c merely to fix an employee address when the other information is correct. Name-only corrections and errors involving a tax year or employer identifier also have special instructions. Describe the actual error before choosing a form.
## Original example: compare two selected fields
Assume a fictional employer filed a 2025 W-2 with transcription errors. Its payroll records support $45,100 in federal income-tax wages and $3,060 of federal income tax actually withheld. The original form instead displayed $46,500 and $3,200. The employer confirms the underlying payroll records, not the inflated form entries, are correct.
In this limited example, the issuer’s correction identifies $46,500 as the previously reported Box 1 amount and $45,100 as the correct amount. The wage difference is a $1,400 reduction. Box 2’s reported withholding decreases by $140, from $3,200 to $3,060.
**Fictional original-versus-corrected field comparison**
| Selected field | Previously reported | Correct information | Change |
| --- | --- | --- | --- |
| Box 1 federal wages | $46,500 | $45,100 | −$1,400 |
| Box 2 federal income tax withheld | $3,200 | $3,060 | −$140 |
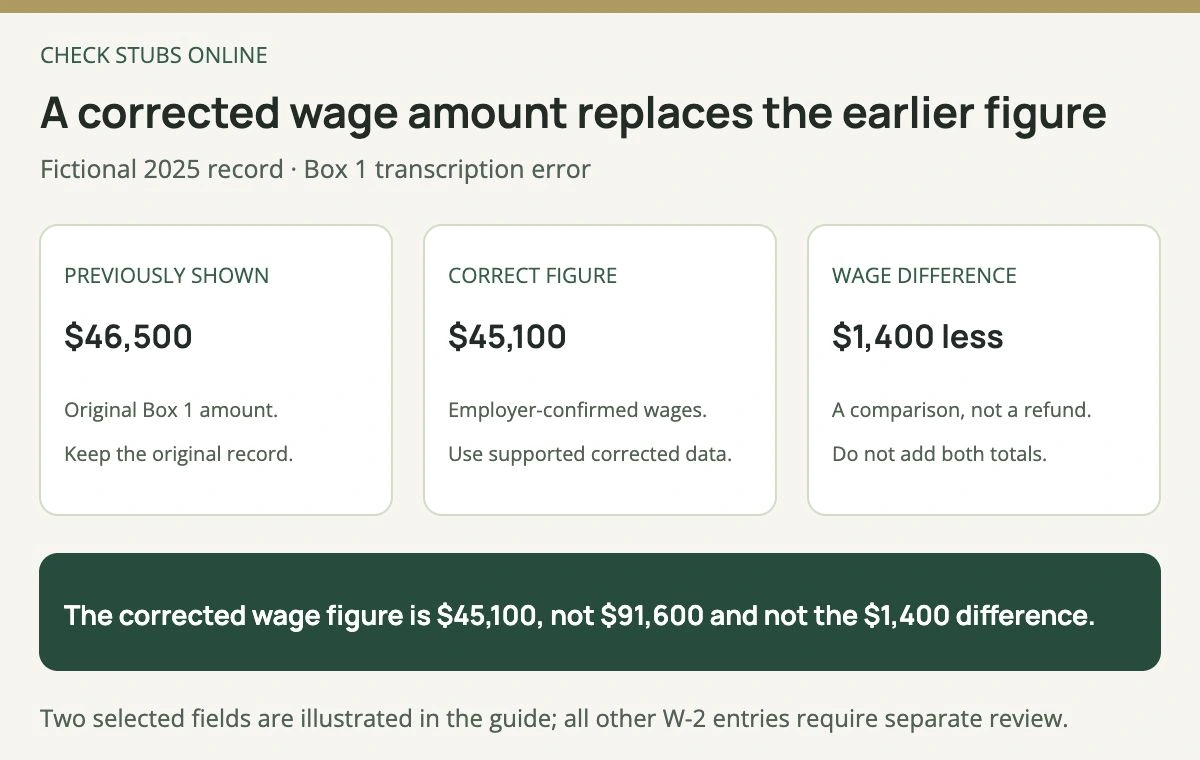
This is a form-transcription example, not an employer refunding taxes or recovering wages. The correct wage amount is the supported replacement value; the difference is only a reconciliation aid.
Do not add $46,500 and $45,100 and report $91,600. Do not report only the $1,400 difference as annual wages either. The same warning applies to withholding: adding $3,200 and $3,060 would overstate the correct reported withholding of $3,060.
The $1,400 and $140 changes do not establish the change in the person’s tax bill. Wages and withholding affect different parts of a return, and other income, deductions, credits and filing facts matter. Review the whole return rather than treating one box difference as a promised refund.
## Read the correction together with the original record
The current [Form W-2c and its employee notice](https://www.irs.gov/pub/irs-pdf/fw2c.pdf) show previously reported and correct-information fields. In an ordinary correction, only affected money fields are completed. A blank elsewhere should not automatically be interpreted as a new zero or proof that the original amount disappeared.
For the example, the reader needs the correct Box 1 and Box 2 amounts, along with the properly reviewed information for other boxes. The two-field illustration does not decide whether Social Security wages, Medicare wages, coded benefits or state entries also need correction.
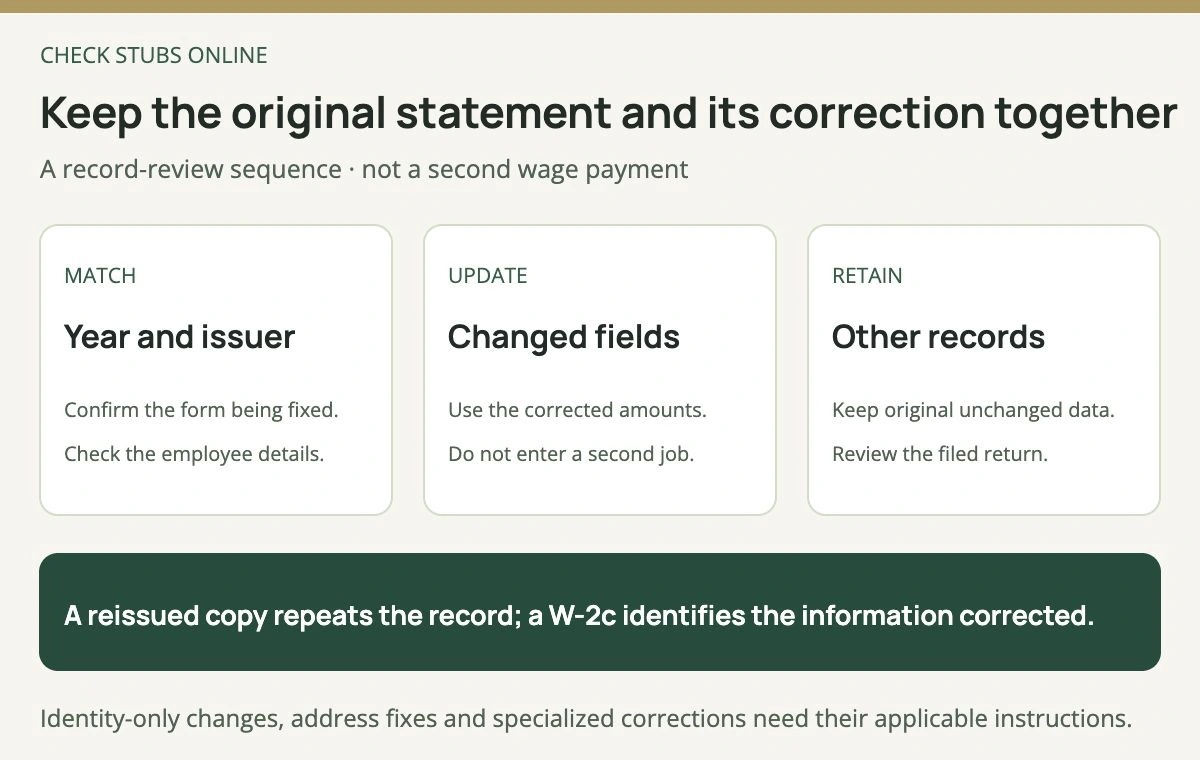
Preserving the original and the issuer’s correction makes the relationship between documents visible. Retain any written explanation of what changed and why.
Match the tax year in the W-2c’s correction field and the employer’s identity. If several W-2s exist under the same employer identifier, ask which original filing or combined amounts are being corrected. Do not invent that relationship by assuming the latest file replaces every form from the employer.
For code-specific context, see our [Box 12 guide](https://blog.checkstubsonline.com/w2-box-12-codes-d-aa-dd-w). For different wage bases, use the [Boxes 1, 3 and 5 guide](https://blog.checkstubsonline.com/w2-boxes-1-3-5-different). A correction should be traced to the field it actually changes.
## If you already filed, compare the return with the corrected data
The employee notice on Form W-2c directs readers to compare the correction with the filed return and addresses Form 1040-X when the corrected amounts change U.S. income tax. It also flags a Medicare-wage correction for review of Form 8959 where applicable. Receiving the form is a reason to review, not a guarantee of a refund or a universal instruction to amend for every identity-only change.
Give the preparer both records and any employer explanation. If you prepare your own return, follow the applicable software and IRS correction instructions; do not enter the W-2c as another unrelated employer solely because the software has an “add W-2” button.
State and local returns need a separate check when their information or the underlying federal figures change. The federal example cannot establish a state amendment requirement. Our [amended-return guide](https://blog.checkstubsonline.com/1040-x-online-amendment-builder-guide) explains the broader preparation task; confirm the procedure and year that apply to your situation.
## Make an employer request that identifies the disputed field
State the year, employer and box, then compare the amount shown with the supporting annual records. For the fictional case: “My 2025 W-2 shows $46,500 in Box 1 and $3,200 in Box 2. The annual payroll detail shows $45,100 and $3,060. Please reconcile those fields and tell me what correction will be issued.”
Send sensitive identity or wage information only through an employer-approved channel. Keep the issued files and your request. If the employer says a form is correct, ask for the reconciliation rather than rewriting its statement yourself. A late payment or noncash item can explain a difference that an ordinary last-paycheck comparison misses.
If a usable W-2 remains unavailable or incorrect, follow the [IRS missing-or-wrong W-2 process](https://www.irs.gov/filing/if-you-dont-get-a-w-2-or-your-w-2-is-wrong). Our [missing W-2 and Form 4852 guide](https://blog.checkstubsonline.com/missing-w2-form-4852) covers that route, including the separate current qualification for qualified tips and overtime deductions. It is different from interpreting a W-2c already received.
## A W-2 PDF builder is not a W-2c filing service
The [Check Stubs Online W-2 builder](https://www.checkstubsonline.com/forms/w2/create) currently offers 2025, as checked November 17, 2026. It prepares a PDF from authorized entries and supports review of actual annual payroll totals. Its current page does not offer a W-2c correction form.
Use the tool only for the preparation task it actually supports. It does not retrieve an employee’s original, decide whether a field is wrong or amend a wage report already filed with SSA. An employer needing a correction should follow the official procedure for that correction, not recreate a second ordinary W-2 and treat the order as filing.
## Reissue and correction questions
### Is a reissued W-2 additional taxable income?
A duplicate copy does not create new wages. Confirm it repeats the same employer, year and amounts rather than describing a separate record.
### Should I add the original W-2 and W-2c amounts?
No. Determine which fields the W-2c corrects and use the supported corrected information with the relevant unchanged original data.
### Does every address correction require filing a W-2c with SSA?
No. The IRS instructions provide specific address-only procedures when the other information is right. Ask the issuer to apply the appropriate route.
### Does a lower Box 1 guarantee a refund?
No. Review all affected tax-return figures, including withholding and other relevant facts. A wage difference is not the same as a tax difference.
The Check Stubs Online Editorial Team reviewed current IRS reissue and correction guidance, checked the live builder, and independently reconciled the original field-comparison example.
## Relevant document tool
Prepare supported annual records without confusing copies and corrections
The ordinary W-2 builder is for authorized PDF preparation. A duplicate request or W-2c correction follows its own issuer process.
[Review the W-2 builder](https://www.checkstubsonline.com/forms/w2/create)
The builder offers 2025 as checked November 17, 2026, not a W-2c form or government filing. It does not retrieve an employer-issued copy or amend a prior wage report.
## Related guides
- [W-2 Box 12 Codes D, AA, DD and W: Meaning and Examples](https://blog.checkstubsonline.com/w2-box-12-codes-d-aa-dd-w)
- [Why W-2 Boxes 1, 3 and 5 Are Different: Wage Examples](https://blog.checkstubsonline.com/w2-boxes-1-3-5-different)
- [Missing W-2? Form 4852, Payroll Records and Filing Steps](https://blog.checkstubsonline.com/missing-w2-form-4852)