---
title: "2026 W-2 and 1099 Deadlines: What Is Due in 2027?"
description: "Check 2027 deadlines for 2026 W-2, 1099-NEC and 1099-MISC records, including recipient copies, filing methods, holiday adjustments and extensions."
url: "https://blog.checkstubsonline.com/w2-1099-deadlines-2027"
datePublished: "2026-11-01"
---
# 2026 W-2 and 1099 Deadlines: What Is Due in 2027?
Check 2027 deadlines for 2026 W-2, 1099-NEC and 1099-MISC records, including recipient copies, filing methods, holiday adjustments and extensions.
Published: 2026-11-01
By [Check Stubs Online Editorial Team](https://blog.checkstubsonline.com/editorial-policy#editorial-team)
**For 2026 wages and payments, the ordinary federal W-2 and 1099-NEC deadline is February 1, 2027, for both recipient statements and agency filing.** Most 1099-MISC recipient statements share that date, but statements reporting amounts in boxes 8 or 10 are due February 16. The ordinary 1099-MISC filing dates are March 1 on paper and March 31 electronically. Extensions, disaster relief and special reporting situations can change a deadline.
Reviewed November 1, 2026 · U.S. federal information returns for tax year 2026, normally delivered or filed in 2027. This calendar covers ordinary W-2, 1099-NEC and 1099-MISC obligations; state requirements and special cases need separate review.
A year-end statement has two destinations: the person receiving it and the government agency receiving the return. Completing a PDF does not satisfy both jobs. Keep separate records of delivery, filing and acceptance, even when a payroll or filing service handles them together.
Start by confirming which form the payment actually requires. Our [1099-NEC versus 1099-MISC comparison](https://blog.checkstubsonline.com/1099-nec-vs-1099-misc) explains the distinction. Use the [forms catalog](https://www.checkstubsonline.com/forms/) to find document-preparation tools, then confirm the supported tax year and your separate filing route.
## In this guide
1. [2027 deadline calendar for 2026 records](#deadline-calendar)
2. [Choose the correct reporting year](#deadline-year)
3. [Separate recipient delivery from filing](#deadline-destinations)
4. [Count forms for electronic filing](#deadline-electronic)
5. [Build a practical year-end workflow](#deadline-workflow)
6. [Handle extensions and missing records](#deadline-extensions)
7. [Deadline questions](#deadline-faq)
## When are 2026 W-2s and 1099s due in 2027?
The following dates apply without an approved extension or applicable relief. “Recipient” means the employee or other payee; “agency” means the SSA for W-2s and the IRS for the two 1099 types shown.
**Ordinary federal deadlines in 2027 for tax year 2026**
| Return | Recipient statement | Agency paper filing | Agency electronic filing |
| --- | --- | --- | --- |
| W-2 | February 1, 2027 | February 1, 2027 · SSA | February 1, 2027 · SSA |
| 1099-NEC | February 1, 2027 | February 1, 2027 · IRS | February 1, 2027 · IRS |
| 1099-MISC, ordinary recipient rule | February 1, 2027 | March 1, 2027 · IRS | March 31, 2027 · IRS |
| 1099-MISC reporting amounts in boxes 8 or 10 | February 16, 2027 | March 1, 2027 · IRS | March 31, 2027 · IRS |
The [2026 W-2 instructions](https://www.irs.gov/instructions/iw2w3) explicitly set February 1, 2027, for SSA filing and ordinary employee delivery. The [1099-MISC/NEC instructions](https://www.irs.gov/instructions/i1099mec) set the ordinary January 31 NEC deadline and different MISC filing deadlines; weekend and holiday adjustments produce the dates above.
January 31 and February 28, 2027, are Sundays. February 15 is Washington's Birthday on the [official federal holiday calendar](https://www.opm.gov/policy-data-oversight/pay-leave/federal-holidays/#url=2027). The MISC recipient exception therefore moves to Tuesday, February 16. [IRS Publication 1099 for 2026](https://www.irs.gov/publications/p1099) identifies boxes 8 or 10 for that exception and explains the next-business-day rule. Check additional applicable holidays and any relief specific to your situation.
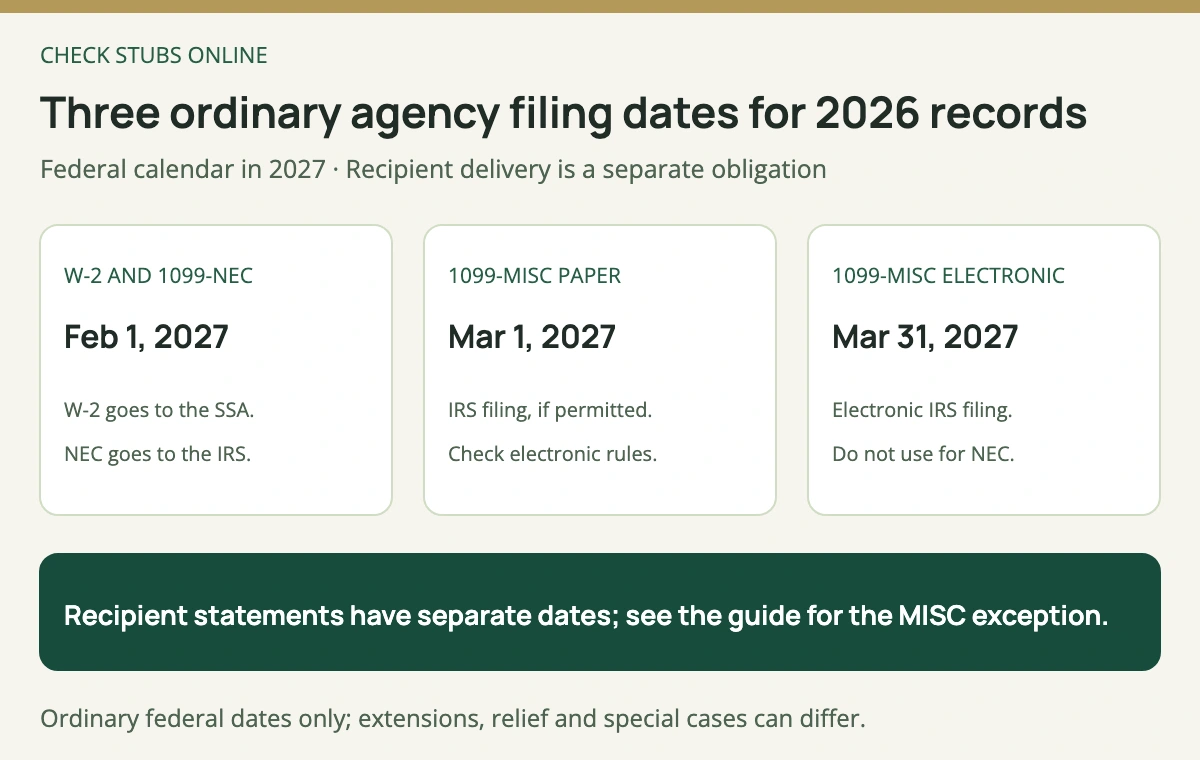
These are agency filing dates. The table separately identifies recipient delivery, including the February 16 MISC exception.
## The tax year is different from the year you send the statement
A 2026 W-2 usually reaches the employee in early 2027. That does not turn it into a 2027 W-2. For wages, follow the payment year rather than assuming the work period alone decides the reporting year.
For example, an employee works December 21–31, 2026, but receives those wages January 8, 2027. Under the W-2 calendar-year payment rule, those wages belong on the 2027 W-2. Conversely, wages actually paid in December 2026 belong in the 2026 record, subject to the applicable wage-reporting rules.
Use the relevant year's instructions to decide which business payments are reportable. The IRS's [information-return guidance](https://www.irs.gov/businesses/small-businesses-self-employed/am-i-required-to-file-a-form-1099-or-other-information-return) describes a $2,000 threshold for certain nonemployee compensation paid in 2026. That is not a universal threshold for every 1099 category, and backup withholding can create reporting obligations regardless of the payment amount. Resolve classification and exceptions before adding a deadline to your calendar.
## Giving someone a copy is different from filing with an agency
For each return, record three milestones: the statement was prepared, the recipient was furnished the required copy, and the agency submission was accepted or otherwise completed through the permitted filing method. A downloaded PDF proves only the first milestone unless another service explicitly performs the others.
Use the correct agency. W-2 filings go to the Social Security Administration; 1099-NEC and 1099-MISC filings go to the IRS. Do not send employment-tax payments with a W-2 package or assume a state submission also completes the federal obligation.
The W-2 instructions explain that a properly addressed statement mailed by the due date meets the furnishing requirement. That is different from promising physical arrival on that day. Electronic recipient delivery has its own requirements; entering an email address into a document builder does not establish compliant delivery or consent.
Keep a recipient-delivery record and the agency filing acknowledgement separately. If a filing platform rejects a record, saving the rejection is useful evidence of what happened, but it does not make the rejected submission an accepted return.
## How does the 10-return electronic filing threshold work?
The IRS's [electronic information-return guidance](https://www.irs.gov/filing/e-file-information-returns) generally requires electronic filing when the applicable aggregate reaches 10 returns, subject to relevant waivers and exemptions. Count the covered return types together under the aggregation rules, rather than treating every form family as a separate allowance of nine paper returns.
Consider a fictional small employer required to file five W-2s, four 1099-NECs and one 1099-MISC for the calendar year. The count is 5 + 4 + 1 = 10. The single MISC return does not create a stand-alone paper-filing exception merely because there is only one of that form.
Count returns, not the employee's multiple copy pages or the number of envelopes you plan to send. Confirm which return types and exceptions apply to your actual filing population. A permitted waiver changes how you may file; it does not automatically move the due date.
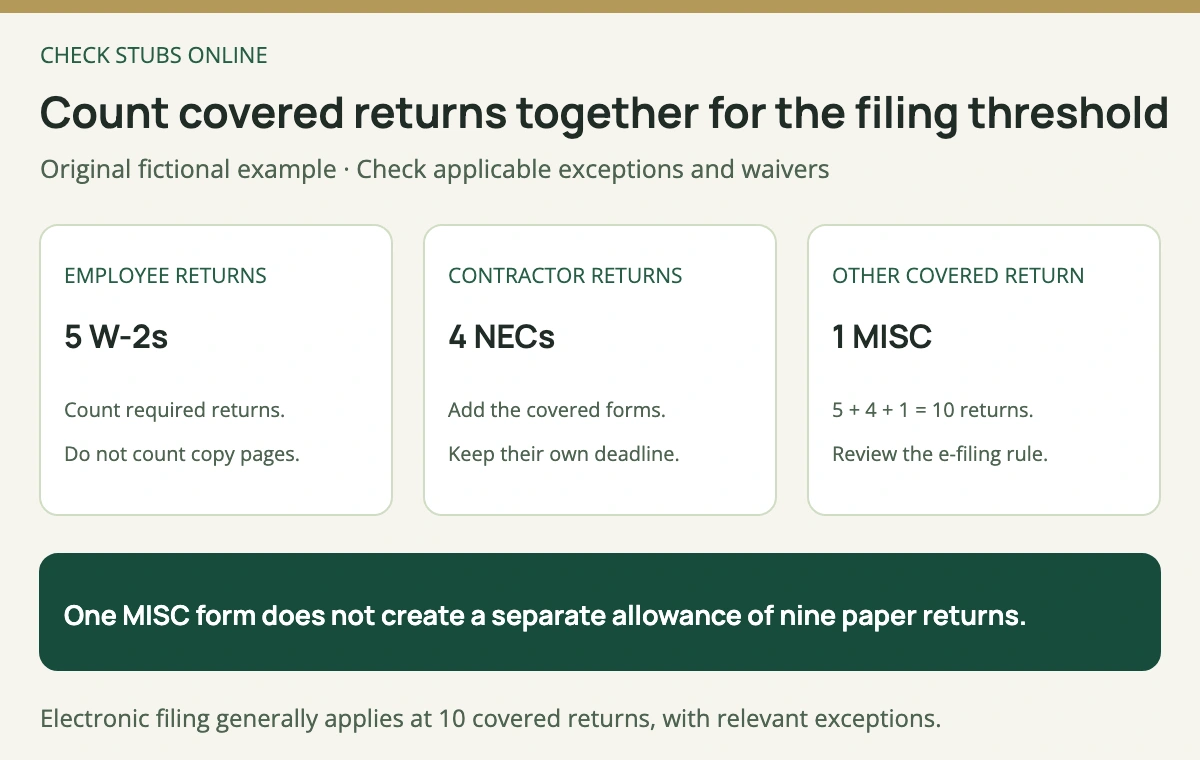
The example counts required returns across types. It does not count recipient copy pages or transmittals as extra W-2 or 1099 returns.
## A workflow that catches problems before the deadline
1. **Reconcile the payment ledger.** Compare payroll totals and reportable vendor payments with the source records. Separate duplicates, reimbursements and payments requiring another reporting treatment.
2. **Confirm identity details securely.** Resolve the payee's legal name, taxpayer identification details and current address through an appropriate channel. Avoid putting full identifiers into ordinary email subject lines.
3. **Check the supported tax year.** A tool showing a prior-year W-2 does not establish that it supports 2026. Our [2025 W-2 preparation guide](https://blog.checkstubsonline.com/w2-generator-2025-guide) is explicitly year-specific.
4. **Confirm filing access early.** Verify that your SSA or IRS filing service supports the relevant year and return type, and complete any enrollment before the last day. Do not assume a processing-year portal is already open.
5. **Review the finished statement.** Check amounts, form type and recipient details against the ledger. The [1099-NEC tool guide](https://blog.checkstubsonline.com/1099-nec-generator-guide) and [1099-MISC tool guide](https://blog.checkstubsonline.com/1099-misc-generator-guide) concern preparation, not a guarantee that the return has been filed.
6. **Close both destination tasks.** Save recipient-delivery evidence and agency acknowledgements. Set a follow-up for rejected files rather than marking them complete automatically.
## Extensions, late statements and corrections need separate decisions
An information-return filing extension does not automatically extend the recipient deadline. The IRS's [Topic 803](https://www.irs.gov/taxtopics/tc803) distinguishes Form 8809 filing requests from Form 15397 recipient-statement requests. W-2 and 1099-NEC filing extensions are not automatic and require the applicable qualifying conditions. Do not assume the ordinary automatic extension rules for other returns apply to them.
Our [Form 8809 guide](https://blog.checkstubsonline.com/form-8809-online-information-return-extension-guide) explains the preparation distinction. Check the current instructions, timing and submission method before relying on relief. An income-tax return extension is a separate matter again.
If a statement is missing, first contact the issuer and confirm the delivery address or authorized portal. A recipient should not invent an issuer statement to fill a gap. See [how to obtain a 1099 copy](https://blog.checkstubsonline.com/get-copy-of-1099-online) for source options. If an issued statement is wrong, ask the responsible issuer about the appropriate correction process and retain the corrected version.
## Deadline questions
### Does electronic filing always give me until March 31?
No. The ordinary W-2 and 1099-NEC agency deadline remains February 1, 2027, even when filed electronically.
### Is February 16 the deadline for every 1099-MISC recipient?
No. That exception concerns MISC statements reporting amounts in boxes 8 or 10. The ordinary recipient date in the table is February 1.
### Does this calendar include state filing?
No. Check each relevant state's requirements separately, including any rules about federal/state filing arrangements.
### Can I print the online W-2 Copy A and mail it to SSA?
The IRS warns that its informational online Copy A is not a printable filing version. Use an approved paper form or the appropriate electronic filing route.
The Check Stubs Online Editorial Team checked current federal instructions, calendar weekdays and the original aggregate-count example. This guide is educational; the filer remains responsible for the correct form, year, method and deadline.
## Relevant document tool
Choose your form, confirm its year and plan the filing route
Find the relevant document tool, review its supported tax year and compare every field with your actual records. Track recipient delivery and agency filing separately.
[Explore the forms catalog](https://www.checkstubsonline.com/forms/)
Document preparation alone does not file a return, deliver recipient copies or extend a deadline.
## Related guides
- [Form 8809 Online: Prepare an Information-Return Extension Request](https://blog.checkstubsonline.com/form-8809-online-information-return-extension-guide)
- [1099-MISC Generator: Review Rents, Royalties and Other Payments](https://blog.checkstubsonline.com/1099-misc-generator-guide)
- [1099-NEC Generator: Review 2025 and 2026 Contractor Payments](https://blog.checkstubsonline.com/1099-nec-generator-guide)